Mitigating Crop Damage from Natural Disasters: Lessons from Rainstorms and Floods


Floods and severe rainstorms are a growing source of crop losses in Nigeria, and the claims that follow are rarely simple. Damage has to be measured on the ground, tied to the insured peril, and valued against policy terms that often turn on details settled long before the loss.
This article looks at two anonymised agricultural claims: a flood on a Moringa plantation and a rainstorm on a large maize farm. We cover the risk factors present before each loss, how the claims were investigated and quantified, and what insurers, brokers and claims managers can take from them.
How floods and rainstorms damage crops
The two perils cause different kinds of loss, and that shapes what an adjuster looks for on site.
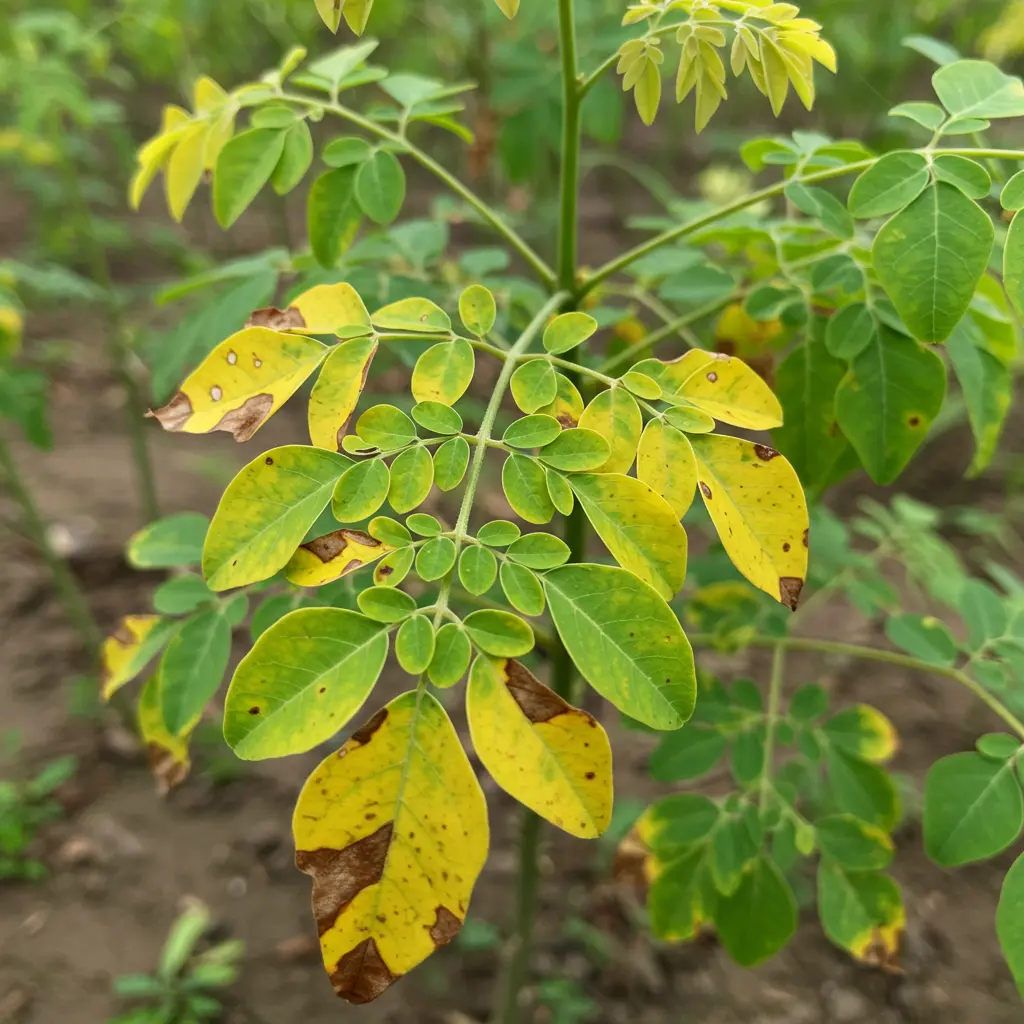
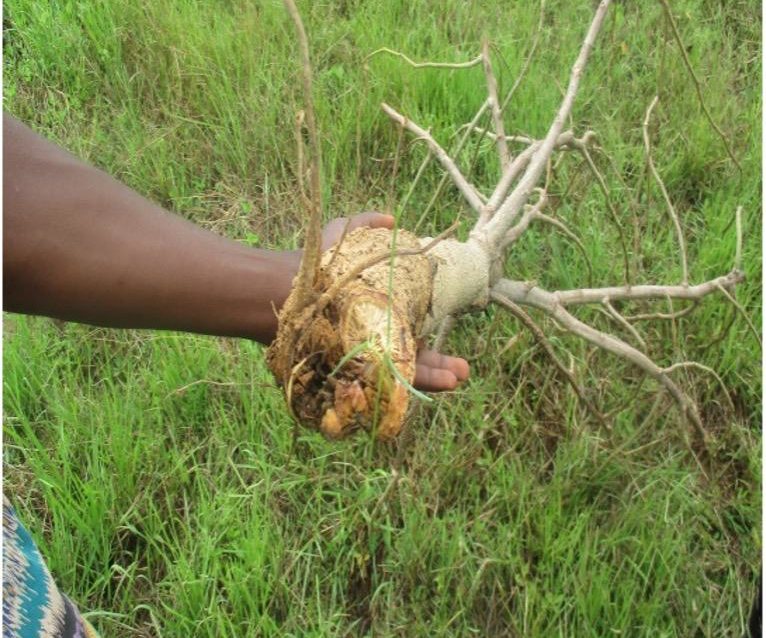
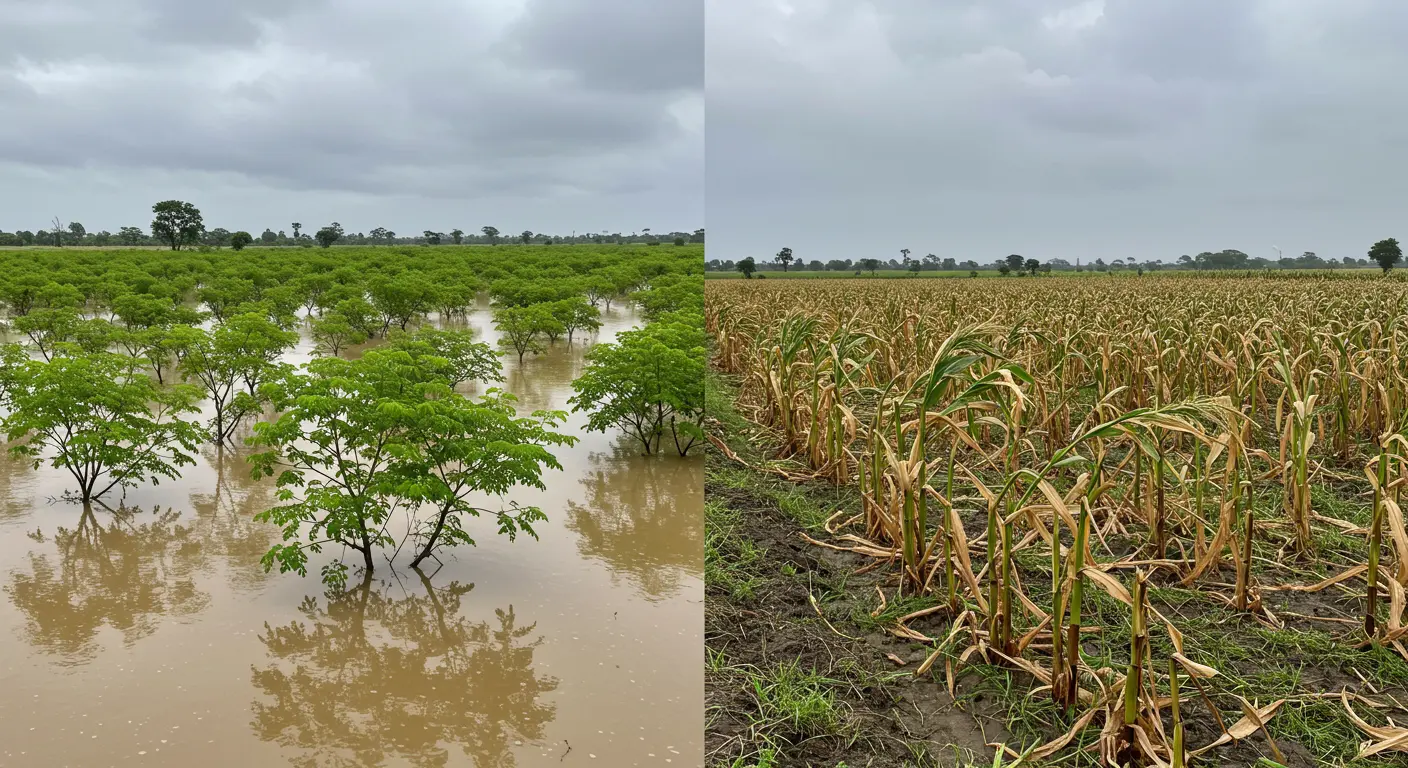
Flooding. Standing water does more than wash crops away. Prolonged waterlogging starves roots of oxygen, stops nutrient uptake and can lead to root rot and plant death. Floodwater can also break plants, deposit silt, leach nutrients from the soil and encourage fungal disease. How bad the damage is depends on the depth and duration of the water, the lie of the land, soil type and drainage, and the crop's growth stage and tolerance. Water-sensitive crops such as Moringa suffer badly.
Rainstorms. A severe storm usually combines heavy rain with strong wind. Wind snaps stems or flattens plants (lodging), which can make mechanical harvesting difficult or impossible. Heavy rain on exposed or sloping ground strips topsoil, undermines roots and carries nutrients away. Intense rainfall can also overwhelm drainage and cause local flash flooding outside recognised flood plains.
The two farms before the loss
Case A (flood) was a mechanised farm growing Moringa trees, a crop known to be intolerant of waterlogging. Case B (rainstorm) was a large mechanised maize operation using hybrid seed.
Several risk factors were in place before either loss occurred:
- Topography. Both farms had land sloping towards nearby rivers. In Case A the flood damage was concentrated in these low-lying sections. In Case B the slope contributed to erosion and wash-off.
- Crop vulnerability. Moringa's intolerance of excess water made the Case A flood far more damaging than it might have been for a hardier crop.
- Inadequate mitigation. Case A had drainage trenches, but they were not sufficient for the scale of the flooding. Having mitigation in place is not the same as having enough of it.
- Pre-existing damage. In Case B we found signs of erosion on parts of the farm that pre-dated the storm, a weakness that may have made the storm's effect worse.
- Area discrepancy. In Case A the policy covered 40 hectares of Moringa, but 60 hectares had actually been planted. This underinsurance had a major effect on the settlement.
The losses and how they were investigated
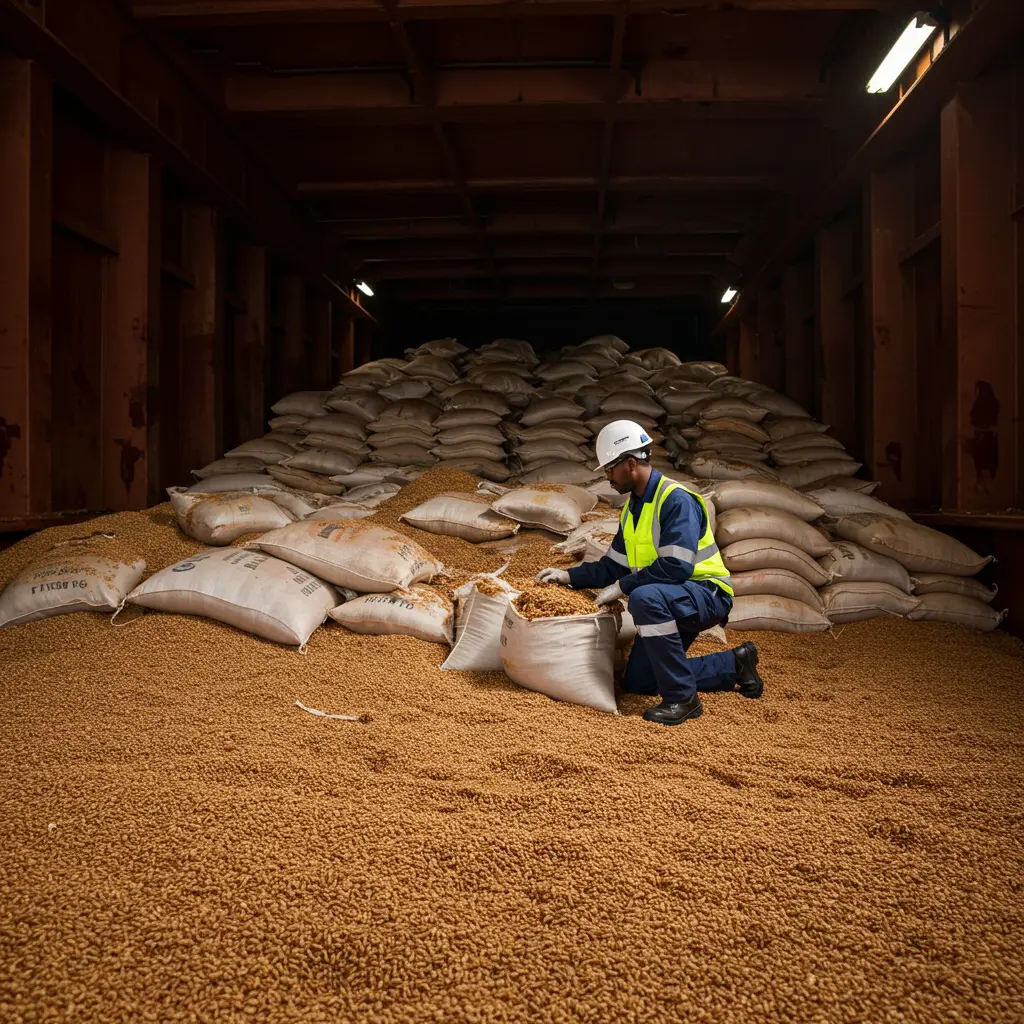
In Case A, heavy rain over five consecutive days flooded the plantation, worst in the low ground near the river. In Case B, a single severe storm of heavy rain and strong wind broke maize stems and caused significant topsoil erosion across several blocks.
In both cases we were appointed soon after notification, which allowed early site inspections. Speed matters in crop claims because the evidence changes quickly.
The investigation drew on several sources:
- Physical inspection confirmed the visible damage: waterlogged trees in Case A, broken stems and erosion in Case B.
- Meteorological reports were used in Case A to confirm that the insured peril had occurred.
- Agronomic evidence. The farm agronomist's report in Case A confirmed the effect of waterlogging on the trees.
- GPS measurement was used in both cases to establish the affected area. The measured figures sometimes differed slightly from those in the claim.
- Plant counts were checked within the affected areas.
Case A also showed a familiar problem: the insured was slow to provide full documentation, including detailed cost breakdowns, which delayed the adjustment. Being clear and specific about what is needed, early, saves time.
Valuing the loss and applying the policy
Both claims were under Multi-Peril Crop policies and both were settled on an input cost basis. The starting point was the verified input cost per hectare multiplied by the measured damaged area. We checked the claimed costs against farm records and benchmarks before accepting them.
From there, the policy terms were applied in turn:
- Unspent inputs. In Case B, fertiliser that had not yet been applied to the damaged blocks before the storm was deducted. The insured cannot recover inputs it never spent.
- Salvage. In Case A, a number of trees in the affected area were judged recoverable and their value was deducted. In Case B, a salvage value of 20% was agreed and deducted from the maize loss.
- Excess. The policy excess was 20% of the adjusted loss in both cases: under the Flood section in Case A and under "Other Perils", which included rainstorm, in Case B.
- Average. Because only 40 of the 60 planted hectares were insured, the average clause applied in Case A. The loss was reduced in proportion to the sum insured against the full value at risk, which cut the settlement substantially.
The outcomes differed for different reasons. Case A was dominated by underinsurance. Case B turned on separating storm damage from erosion that was already there, and on distinguishing inputs actually used from those planned but not yet applied. In both, accurate area measurement and consistent treatment of salvage and excess were central.
Lessons for insurers and claims managers
- Verify the planted area at underwriting. Do not rely on the insured's declaration. A gap between insured and cultivated hectares will surface at claim stage through the average clause, when it is hardest to discuss.
- Look at the site, not just the proposal form. Slopes, distance to rivers, the capacity of existing drainage and signs of earlier erosion all affect the risk and should inform pricing and risk advice.
- Know the crop. A crop's tolerance of water, wind or erosion changes the likely severity of a loss.
- Agree the valuation basis in the wording. Ambiguity over peril definitions or the basis of settlement (input cost or market value) leads to disputes. Sums insured should reflect the whole cultivated area.
- Inspect early and measure objectively. Prompt site visits preserve evidence. GPS measurement, plant counts, weather records and agronomist reports give the adjustment a factual footing.
- Separate event damage from existing conditions. Pre-existing erosion or other weaknesses should be identified and excluded from the loss.
- Check costs line by line. Verify input costs against farm records and deduct anything not yet spent at the date of loss.
- Feed claim findings back to underwriting. Recurring issues such as underinsurance, poor drainage or slope-related erosion should shape future risk assessment, wording and advice to farmers, including encouragement of better drainage, erosion control and more tolerant crop varieties.