Mechanical vs. Electrical Failures: Differentiating Causes in Equipment Breakdown Claims


When a generator or other industrial machine stops working, the first explanation offered is often the wrong one. Mechanical and electrical failures can look the same at the outset, and a misdiagnosis leads straight to the wrong policy response and the wrong settlement.
This article walks through an anonymised claim we handled for the breakdown of an industrial diesel generator under the Mechanical/Electrical Breakdown extension of an Industrial All Risk (IAR) policy. It covers how we established the cause, how the repair costs were tested, and how underinsurance changed the outcome more than anything else.
Where diesel generators fail
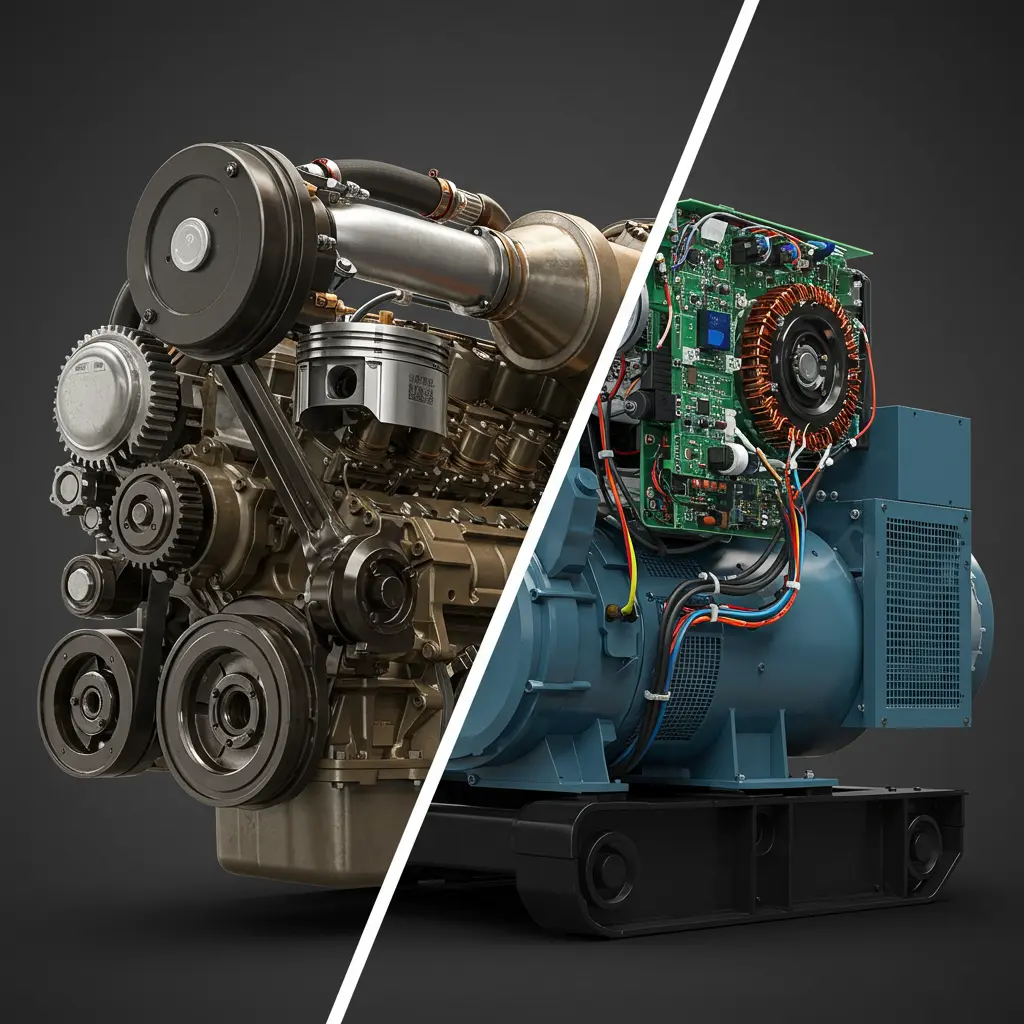
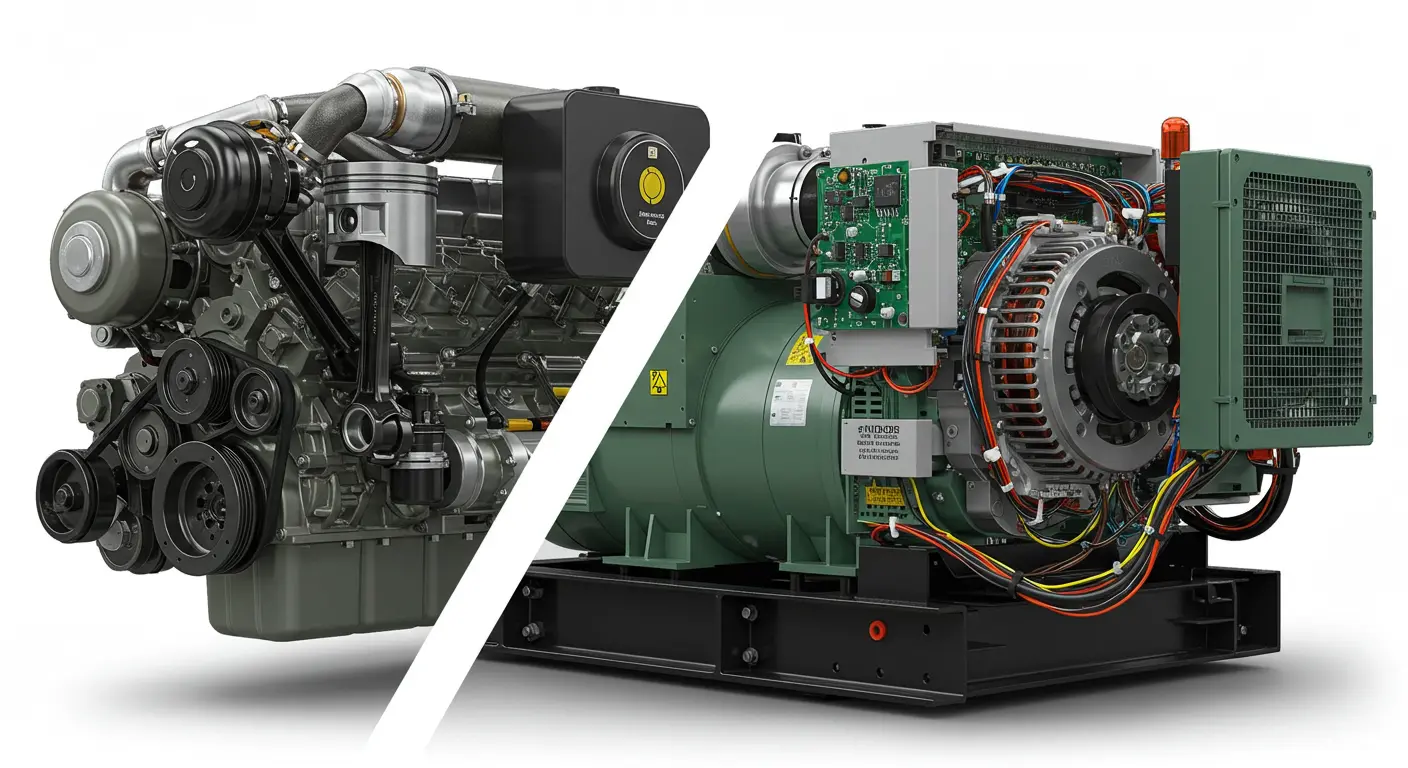
A diesel generator has two halves: the engine, which is the prime mover, and the alternator, which turns the engine's mechanical energy into electricity. Each has its own typical faults.
Mechanical systems
- Engine: pistons, cylinders and crankshaft carrying out the combustion cycle.
- Fuel system: moves diesel from the tank to the engine through the lift pump and injectors.
- Lubrication system: circulates oil to reduce friction and wear.
- Cooling system: circulates coolant through the radiator and engine jackets.
- Exhaust system: carries away combustion gases.
Common mechanical failures include fuel delivery problems such as a failed pump or blocked injectors, loss of lubrication, overheating from cooling faults, and wear leading to component breakage.
Electrical systems
- Alternator (gen-head): the stator and rotor that together produce the electrical output.
- Exciter: helps create the magnetic field.
- Voltage regulator: keeps output voltage steady.
- Control panel: instruments, controls and safety shutdowns.
Typical electrical failures are winding faults, short circuits, regulator failure, control panel faults and damage from external surges.
Why the symptoms mislead
A generator that will not start, or stops without warning, could be suffering from fuel starvation or from a control fault. The symptoms overlap. In the case below, the first report pointed to an electrical surge. The real cause was mechanical.
The generator and its risk profile
The unit was an 800kVA soundproof diesel generator at the factory of a large steel manufacturer. It was one of three backup generators supporting the national grid supply, and it powered the factory, the administrative building and on-site expatriate housing during outages.
Maintenance was good. An in-house team carried out daily checks on water, oil and fuel levels, and preventive maintenance, including lubricant and filter changes, was done every 200 running hours. We reviewed the maintenance logs and found them satisfactory. Because the grid supply was generally reliable, the generators were not heavily used.
Valuation was another matter. A pre-loss survey had produced an inventory, but the declared value for this generator was only about a sixth of its actual replacement value at the time of loss. That gap decided the size of the settlement.
What happened and how we investigated
The generator was running normally after a grid outage when it shut down suddenly one afternoon in November 2024. The on-site team could not restart it and brought in an alternative 1000kVA generator to restore power.
The insured notified its broker and insurer promptly and called in the generator supplier's representative. Insurers then appointed us. Working with a consulting engineer, we visited the site, inspected the generator before any repair, interviewed key staff including the Electrical Maintenance Manager, and reviewed the documents.
The supplier's report attributed the breakdown to a "sudden electrical surge that resulted in mechanical failure" but did not commit to a root cause. We found no physical evidence of a surge: no burnt components and no signs of a short circuit.
Our technical analysis showed the diesel lift pump had failed. That starved the engine of fuel, causing it to stall, and caused consequential damage to the fuel system, specifically the six diesel injector nozzles.
Testing the repair costs
The insured submitted a repair quotation from the supplier's representative, covering repairs and a visit charge. We went through it line by line.
- Disallowed: items unrelated to the breakdown, including battery terminals, coolant, filters, cables and a pre-existing service offer.
- Reduced: labour, to reflect the smaller scope of work once those items came out.
- Allowed: the lift pump, injector nozzles, a top overhaul kit for decarbonising, cleaning agents, and the supplier's initial inspection visit.
The adjusted loss came out at roughly nine tenths of the quotation. The damaged parts had negligible salvage value.
How the policy responded
With the cause confirmed as mechanical breakdown, the loss fell within the Mechanical/Electrical Breakdown extension of the IAR policy.
The policy carried an 85% condition of average. As the declared value was far below that threshold, average applied, and the adjusted loss was scaled by the ratio of declared value to replacement value. The insured was therefore entitled to only about a sixth of the adjusted loss.
The deductible for the breakdown extension, set by the sum insured tier, was then taken off. The net settlement we recommended was roughly an eighth of the original quotation. Underinsurance, not the cause of failure or the repair scope, was the largest single factor.
Lessons for insurers and claims managers
- Do not take supplier reports at face value. An unclear or noncommittal conclusion, even from the manufacturer's representative, needs independent technical review. Here it pointed in the wrong direction.
- Separate the root cause from consequential damage. The lift pump failure was the cause; the injector damage followed from it. Getting this right defines what is recoverable.
- Check every line of the repair quotation. Strip out consumables, unrelated service work and betterment, and test labour against the actual scope.
- Ask for maintenance records. Good records support a claim and answer allegations of neglect. Missing records make a claim harder to resolve.
- Verify declared values at inception and renewal. An inventory list is not a valuation. Compare declared values with current replacement costs for high-value machinery.
- Explain average early. Brokers and insureds should understand how average works before a loss, not when the settlement figure arrives.
- Feed claim findings back to underwriting. Valuation gaps and maintenance evidence from claims should inform risk assessment, policy wording and the advice given to policyholders.