Investigating Explosion Claims: Insights from a Gas Flow line Incident


Explosions in upstream gas infrastructure are among the more demanding claims an energy insurer will see. Getting them right means understanding how the equipment works, what the maintenance records do and do not show, and how the policy treats gradual deterioration against sudden damage.
This article walks through an anonymised claim we worked on involving a gas flow line rupture at an onshore facility in Nigeria. It covers the risk factors before the loss, how the claim was investigated and adjusted, how the policy terms were applied, and what insurers and claims managers can take from it.
How gas flow lines work and where they fail
A flow line carries natural gas, often at high pressure, from the wellhead to gathering or processing facilities. A typical onshore well, like the one in this case, has three main parts:
- Wellhead and Christmas tree: the surface assembly that supports the well and controls pressure. The Christmas tree is an arrangement of valves, spools and fittings used to control flow, shut in the well and manage production.
- Flow line: the pipe from the Christmas tree to downstream systems. In this case it was a 4-inch (10.16 cm) stainless steel line.
- Safety systems: surface safety valves on the tree, and sometimes subsurface safety valves downhole, which shut off flow automatically when pressure or other conditions go outside set limits.
The line in this case ran at about 2,800 psi. At those pressures, the main risks are:
- Corrosion: internal, from water, CO2 or H2S in the gas stream, and external, from the environment. Both thin the pipe wall over time.
- Pressure fluctuations: surges or build-ups that exceed what a weakened section can hold.
- Ageing and fatigue: normal wear over the working life of the line.
- Maintenance gaps: infrequent wall thickness surveys, no corrosion inhibition, or poor repairs.
- Third-party damage: excavation or other activity near the line, less likely on a secured site.
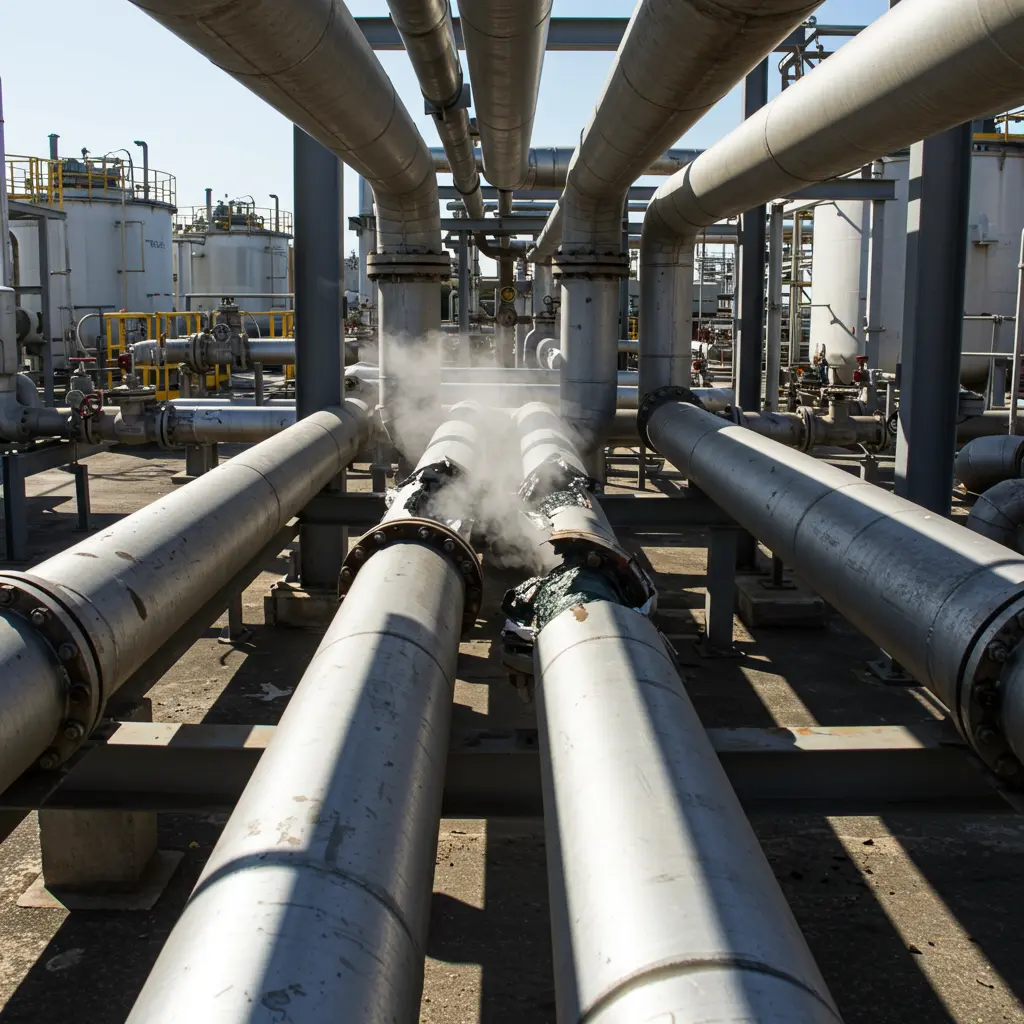
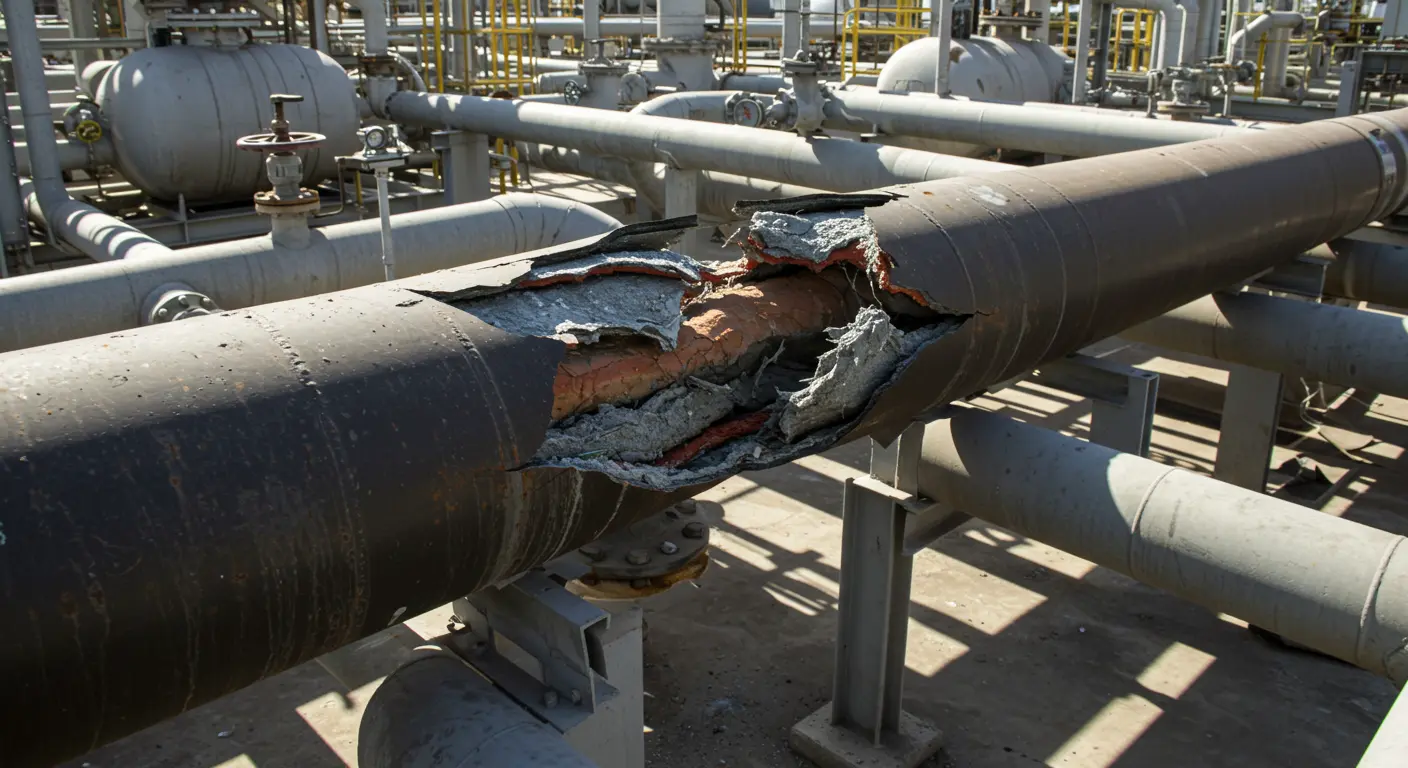
A rupture can release a large volume of flammable gas that then ignites. The sudden release of pressure can also cause explosive damage on its own, without any fire. That is what happened here.
The risk before the loss
The facility was a gas plant operated by an independent Nigerian energy company under a joint venture agreement. Two pre-loss factors shaped the claim.
Ageing, acquired infrastructure
The flow line and wellhead were part of assets the operator acquired in 2010. During the investigation, no evidence was produced to show that this flow line had been replaced or upgraded since the previous operator installed it.
Integrity management
The insured described daily checks by an in-house team and scheduled preventive maintenance by specialist contractors, and kept records such as Well Intervention Daily Reports. But the insured's own post-incident report found an "absence of a system for ensuring the integrity of the flow line throughout the lifecycle of the well". It noted that wall thickness surveys on the line had been carried out only once, and that there was no corrosion inhibition injection. When we asked for the most recent corrosion test report on the line, the insured could not produce one.
What this means for underwriting
- Check acquired assets properly. Do not assume integrity management carried on after a change of operator. Ask for dated records: corrosion surveys, wall thickness readings, inhibition schedules. General statements about maintenance are not enough, and the age of the line is a risk factor in itself.
- Make the wording clear. Energy package policies usually give all risks cover for physical damage. The wording should be clear on how gradual processes such as corrosion are treated against sudden events such as rupture, and on how deductibles apply when one event touches different property types or sections. Here the policy had separate deductibles for general property and specific equipment, plus a clause applying the single highest relevant deductible. That made the adjustment straightforward.
The incident
On 22 January 2020, during normal operations, staff heard a loud bang at the wellhead. A "massive wave of red sand" was thrown out, along with a large, rapid release of gas. There was no fire.
The site safety team evacuated personnel, mobilised emergency resources and closed the Christmas tree valves to shut in the well, which stopped the release. Inspection found a ruptured section of the 4-inch flow line and a collapsed section of the nearby perimeter fence wall.
How we investigated
The lead insurer appointed an international adjusting firm and NTLOSS as local adjusters. COVID-19 restrictions and civil protests delayed the site visit until December 2020, by which time the insured had already repaired the line and put the well back into production.
We interviewed the Facility Manager and Production Engineers and reviewed the incident reports, the internal investigation report, maintenance records and operating logs. The Facility Manager disputed that the integrity lapses in the internal report were relevant to this failure. We confirmed, though, that there was no recent corrosion test report for the line.
Taking the evidence, the age of the pipe and the nature of the failure together, our opinion was that the likely proximate cause was a rupture from pressure build-up at a weak point in the ageing line, possibly made worse over time by poor corrosion management or other maintenance gaps.
The claim covered rerouting and building a new flow line section, non-destructive testing (MPI/OPI), corrosion inspection and general wellhead maintenance. We checked it against invoices, purchase orders, daily work reports and completion certificates to confirm what work was actually done and what it cost.
What the policy said
The claim fell under an Energy Package Policy. The explosion and rupture were accepted as sudden and unforeseen physical loss under Section 1 (Physical Damage, All Risks). The costs were then adjusted on the policy's reinstatement basis:
- Betterment: we applied a 20% reduction to the rerouting and new flow line costs, because parts of the new layout improved on the original design.
- Duplicated costs: similar items such as excavation, backfilling, gas testing and welding appeared on invoices for different work packages. We removed the duplicates from both the construction and corrosion inspection costs.
- Unrelated maintenance: general wellhead maintenance was disallowed in full as routine scheduled work, not repair of explosion damage.
- Deductible: as a Section 1 loss to pipeline and wellhead property, the "All Property" deductible applied, being the highest relevant deductible under the policy. It absorbed most of the adjusted loss.
- Joint venture share: the insured held a 45% interest in the joint venture, so underwriters paid 45% of the net adjusted loss.
- Salvage: the damaged pipe had no significant salvage value.
The result was a valid claim on cover, but one where betterment, duplication, maintenance and a large deductible left only a small recovery once the joint venture share was applied.
Lessons for insurers and claims managers
- Treat ageing and acquired assets as a red flag. Ask for dated corrosion surveys, wall thickness readings and inhibition records. If they cannot be produced, that tells you something.
- Test internal reports and statements. Use them for context, then check them against documents and physical evidence. Follow up where staff accounts and reports disagree.
- Go through costs line by line. Separate like-for-like repair from betterment, look for the same work billed under different packages, and strip out routine maintenance.
- Apply the right section and deductible. On multi-section or multi-item losses, check which deductible the wording says applies. Here the single highest deductible decided most of the outcome.
- Remember the joint venture interest. Confirm the insured's share early so reserves reflect what underwriters will actually pay.
- Feed findings back to underwriting. Gaps found on a claim, such as infrequent corrosion testing, should inform risk questions, wording and terms for similar risks.
- Bring in the right specialists. Technical failures like pipeline ruptures, with significant costs attached, need adjusters who know the industry, supported by engineers and forensic accountants where the causation or quantum calls for them.
- Use the findings with the insured. Showing how a specific inspection gap contributed to a loss is a practical way to start a conversation about preventing the next one.