Navigating Marine Cargo Insurance Claims: Lessons from Damaged Goods in Transit


Bulk agricultural cargo is easily spoiled by water, and claims for it turn on fast action at discharge, proper testing and careful handling of recovery rights.
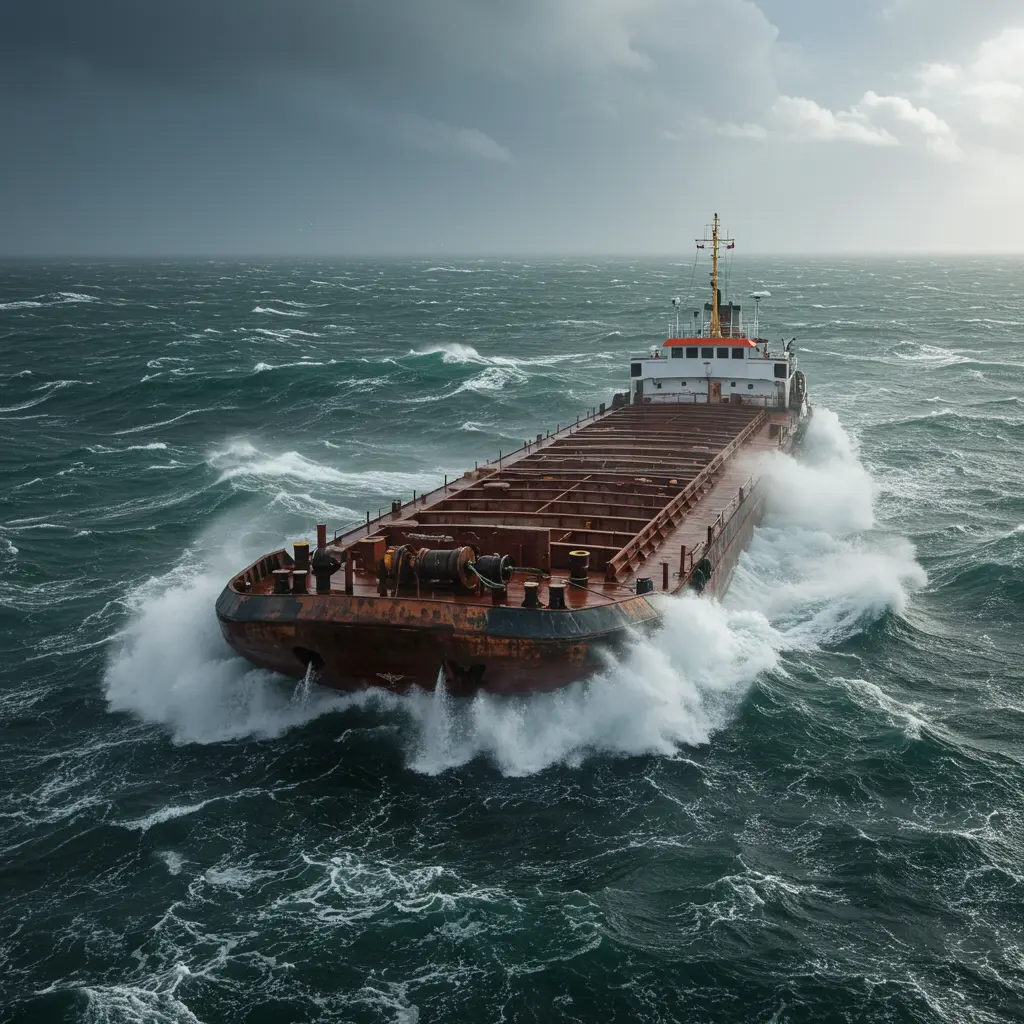
This article looks at an anonymised claim for seawater damage to a bulk shipment of malted barley, found during discharge after a sea voyage to West Africa. It covers the risk factors, how the claim was investigated and adjusted under Institute Cargo Clauses "A", why a subrogation penalty reduced the settlement, and the lessons for insurers and claims managers.
The cargo and the risk
The insured, a beverage company, was importing about 4,000 metric tonnes of malted barley from a European port to a port in West Africa. The shipment was covered under a marine cargo policy on Institute Cargo Clauses "A" (ICC "A"), which gives all risks cover subject to the listed exclusions.
Three factors made this a sensitive risk from the start:
- Cargo sensitivity: malted barley for brewing must stay below a strict moisture threshold, around 4.5%. Any water ingress, especially seawater, can make the affected portion unfit for brewing, which in practice means a total loss of that portion. Barley is hygroscopic: it takes up moisture, and in this case even barley that looked dry failed testing.
- Voyage: the passage from the European loading port may have called at other ports before final discharge. Multi-leg voyages mean longer exposure and more handling than a direct sailing.
- Vessel condition: latent defects in the structure of a bulk carrier's holds are a direct threat to the cargo.
Discharge was expected to follow normal practice: ship's grabs, shore hoppers and possibly suction equipment moving the barley into terminal silos or warehouses, with surveyors for the insured and insurers present to spot problems as they arise.
What happened at discharge
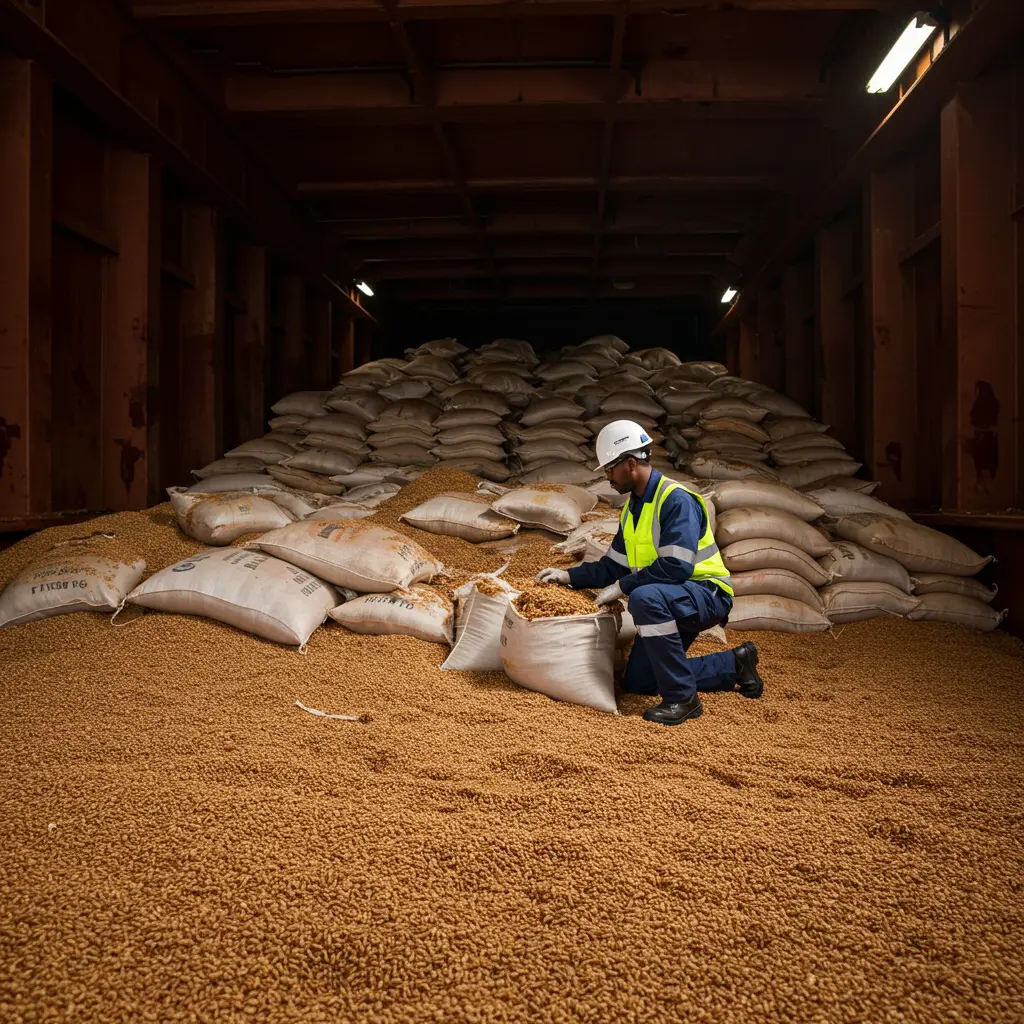
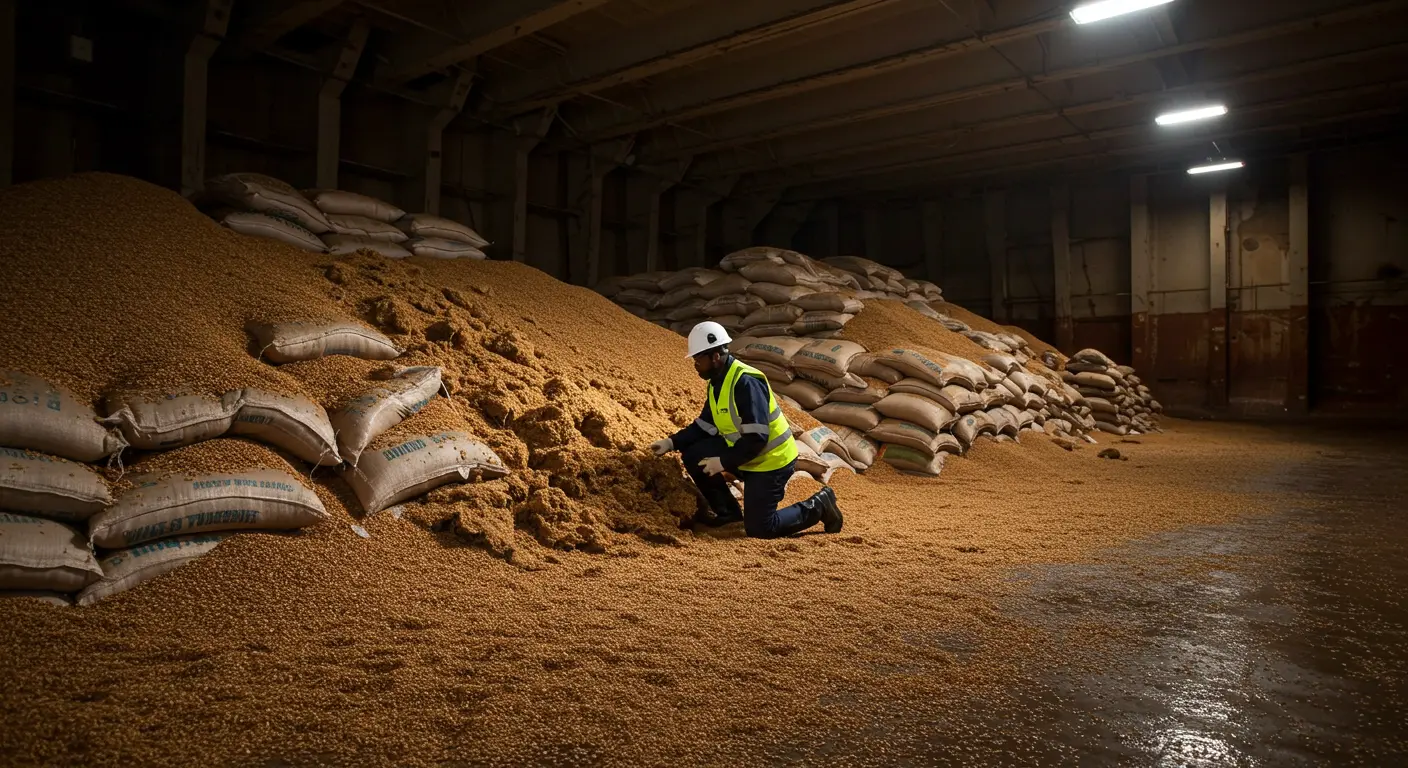
During discharge at the destination port, stevedores saw that barley coming out of one hold looked wet. Discharge from that hold was stopped straight away. Reports first identified it as Hold 1, though some later reports referred to Hold 3.
Investigation found an opening at the bottom of the hold, which had let seawater in during the voyage. A small, unrelated fire on terminal equipment also occurred during discharge. It was put out quickly and played no part in the cargo damage.
How the claim was investigated
- Immediate response: work on the affected hold was halted, the suspect cargo was segregated, and surveyors for the insured and insurer attended quickly.
- Investigation: we interviewed the ship's crew and terminal operators, reviewed vessel logs and documents, and examined photographs. The Hold 1 or Hold 3 question was looked into, although the cause (water ingress) and the effect (wet cargo) were not in doubt.
- Testing: moisture tests were run on samples from the affected hold, including barley that looked dry. Independent laboratory analysis confirmed moisture well above the 4.5% threshold, so the affected cargo could not be used for brewing.
- Quantity: the weight of damaged cargo was agreed through a joint weighing with all parties present.
- Salvage and recovery: the insurer took control of the damaged barley for salvage disposal under the policy. A formal demand was sent to the shipping company, holding it liable for the loss on the grounds that the hole in the hold made the vessel unseaworthy. The shipping company did not respond.
What the policy said
- Cover: the loss was proximately caused by seawater entering through a defect in the vessel, a peril of the sea within ICC "A", and was accepted as recoverable.
- Basis of settlement: the agreed insured value, cost and freight plus the uplift set out in the policy, was applied in proportion to the agreed weight of damaged and rejected cargo.
- Deductible: the standard policy deductible was applied.
- Subrogation: because the carrier did not respond to the liability notice, the insurer's chance of recovering from it was considered prejudiced. Under the policy provisions on prejudice to recovery rights, a penalty was applied to the settlement. It was first set at 20% and negotiated down to 15%.
Where policy wording and documents mattered
The adjustment itself was straightforward once the testing and joint weighing were done. Two points went beyond the physical loss. First, the discharge port named on the marine certificate did not match the port where the cargo was actually discharged. The loss was still covered, but a mismatch like this is an easy source of dispute and should be caught at placement.
Second, the subrogation penalty had a direct effect on what the insured received. Recovery rights are part of the claim, not an afterthought, and the insured needs to understand early how failure to protect them can reduce the settlement.
Lessons for insurers and claims managers
- Know the cargo. For moisture-sensitive goods such as malted barley, understand the quality thresholds before writing the risk and before assessing the loss.
- Match the documents to the voyage. Check that ports of loading and discharge on the certificate reflect the actual voyage, and price in the extra exposure of multi-stop or transhipment routes.
- Act at once. Stop discharge from the affected hold, segregate the cargo and get surveyors and adjusters on site while the evidence is fresh.
- Test, do not judge by eye. Sample cargo that looks dry as well as cargo that looks wet, and have results confirmed by an independent laboratory.
- Resolve discrepancies. Conflicting details such as a disputed hold number should be cross-checked against logs, photographs and witness accounts. Keep survey reports, lab results, joint weight certificates and photos together as the basis of the adjustment.
- Protect recovery rights early. Notify the carrier promptly, pursue the demand, and explain to the insured how prejudiced subrogation can reduce the claim.
- Feed findings back to underwriting. Use what claims reveal about cargo types, vessel condition and voyage patterns to refine risk selection, pricing and policy wording.
- Review your own process. Conflicting reports and slow third-party responses point to where claims procedures can be tightened, for example with better surveyor checklists, clearer communication standards and a set routine for pursuing recoveries.
- Brief insureds. Use outcomes like this one, without breaching confidentiality, to remind insureds why prompt notification, preserving evidence and cooperating on recoveries matter.
- Watch carrier behaviour. How responsive a shipping line is to liability notices is worth recording. It can inform risk assessment and the insured's choice of carrier or contract terms.