The Role of Loss Adjusters in Business Interruption Claims: A Case Study Analysis


Business interruption claims that follow a machinery breakdown are hard to settle well. The physical damage has to be established first, then the financial loss measured and the policy terms applied, and small details in the wording can move the result a long way.
This article follows an anonymised claim at a tyre recycling plant after a power outage damaged its reactors. We set out what happened, how the claim was adjusted, and what claims managers, insurers and brokers can learn from it.
The business and its exposures
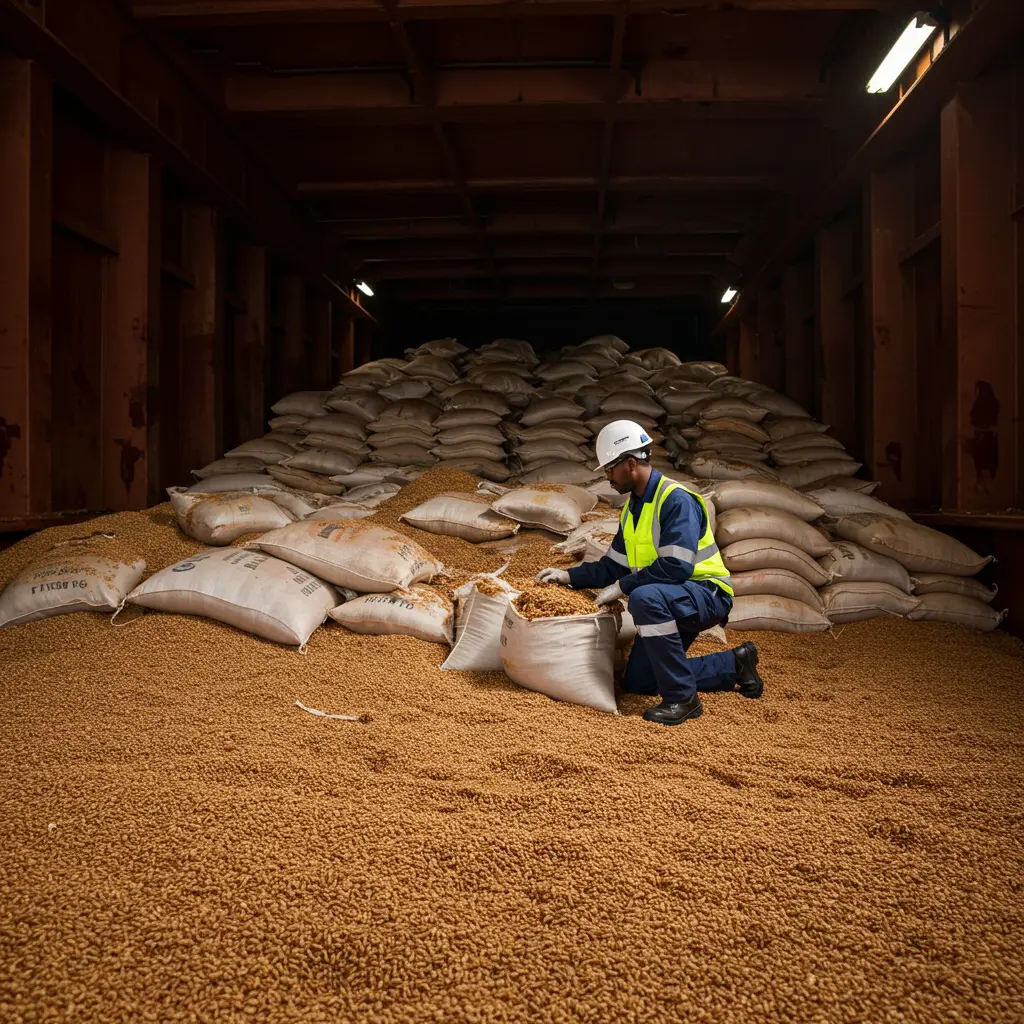
The insured recycled waste tyres using a high-temperature pyrolysis process, producing fuel oil (LPFO), carbon black and scrap wire. The plant ran 24 hours a day, seven days a week, across several production lines in two factory buildings. Power came from the national grid, with on-site generators as backup.
Two exposures stood out. First, the pyrolysis reactors depended on an uninterrupted power supply. An outage threatened not only production but the machinery itself, through thermal stress. Second, the reactor units were more interdependent than a simple count of production lines suggested. That only became clear when the loss occurred.
The business interruption policy covered gross profit, wages and salaries, and auditor's fees incurred in preparing the claim. It included a Departmental Clause and gave a choice of bases for calculating loss of gross profit. Both features shaped the adjustment.
What happened
A grid outage stopped the continuous heating process in the reactors. Power was restored from the generators after about 45 minutes. Shortly after the restart began, operators saw smoke and flames coming from Reactor A. Staff contained the fire with extinguishers and the hydrant system.
The insured's own engineers inspected Reactor A and found swelling and cracks in the reactor chamber, likely caused by thermal shock from the sudden stop and restart. Several days later, Reactor B began vibrating abnormally. Inspection found similar bulging and cracking, and it too was taken out of service.
Reactor C appeared undamaged but could not be run on its own because of process requirements. Production stopped completely. The insured consulted the overseas manufacturer remotely, and on the basis of the findings described to it, the manufacturer recommended replacing both Reactors A and B.
The way the damage came to light in stages shows how difficult it is to judge the full extent of a loss involving specialised equipment in the first few days. The insured's immediate response was sound, but the claim needed outside expertise to confirm the cause, the extent of damage and the likely length of the interruption.
How the claim was adjusted
We first verified the circumstances of the breakdown, confirmed the link between the material damage (the reactor failures following the outage) and the interruption, and established the period of lost production. Given the financial complexity, we appointed forensic accountants to review the insured's records independently and help calculate the loss.
Loss of gross profit
The policy allowed the loss to be calculated on either turnover or output. The insured chose output, meaning the sale value of goods produced. We calculated the production shortfall by comparing expected output, based on performance before the incident, with actual output during the interruption. The verified average selling price per unit was then applied to that shortfall to give the value of lost production.
The rate of gross profit was worked out from the insured's audited accounts, strictly following the policy definition. Uninsured working expenses such as raw materials were excluded. The rate came to 11%, and this was applied to the value of lost production to arrive at the gross profit loss.
Wages and the Departmental Clause
The insured ran separate business segments, including tyre oil and carbon black, each with its own ascertainable trading results. Under the Departmental Clause, we apportioned the wages sum insured according to the company's own allocation of expenses between departments. The tyre oil department accounted for 26% of expenses, so only 26% of the wages sum insured applied to the loss in that department. This was before any question of underinsurance arose.
Auditor's fees
Fees reasonably incurred in producing and certifying the information we needed were covered under the Professional Accountants' Clause, up to the policy sub-limit. We reviewed them and allowed them within that limit.
Underinsurance and the final figure
We tested each sum insured against the value at risk. Gross profit was adequately insured. Wages were not: the sum insured for wages covered only about 21% of the insured's actual annual wage roll, leaving it roughly 79% underinsured. Average was applied to the adjusted departmental wages claim, which reduced that part of the payment substantially.
The adjusted gross profit, wages (after average) and auditor's fees were then totalled, and the policy excess deducted. The excess was the higher of 10% of the adjusted loss or a fixed minimum. The recommended settlement came to a little over a quarter of the amount originally claimed. We also calculated each co-insurer's share.
A gap of that size needs to be explained carefully. Setting out each step of the calculation and the policy clause behind it is what allows the insured, the broker and the insurers to follow and accept the outcome.
Lessons for claims managers and underwriters
- Review sums insured regularly, especially wages. The underinsurance on wages had a direct and large effect on this settlement. Encourage policyholders, usually through their brokers, to check declared gross profit and wage roll figures against their current accounts.
- Understand how the business actually runs. Several production units do not give resilience if they cannot operate independently. Ask about the resilience of the power supply and backup, and whether one failure will stop the whole process. This helps both at underwriting and in estimating the likely scope and length of an interruption.
- Know the wording before a loss. Whether loss is measured on turnover or output, how gross profit is defined (particularly uninsured working expenses) and how a Departmental Clause operates can change the outcome considerably. Claims managers need to be able to interpret and explain these terms.
- Bring in specialists early. Manufacturers, specialist engineers, forensic accountants and loss adjusters each have a part to play in a complex machinery and business interruption claim. Early involvement helps establish cause, extent and likely duration.
- Manage expectations with facts. Where underinsurance or policy terms produce a settlement well below the amount claimed, early and clear explanation based on the adjuster's findings avoids disputes later.
- Feed claim findings back to underwriting and broking. Inadequate sums insured and hidden operational dependencies found during a claim should inform future risk assessment and advice to clients.