Act of God vs. Negligence: Decoding Liability in Marine Insurance Claims


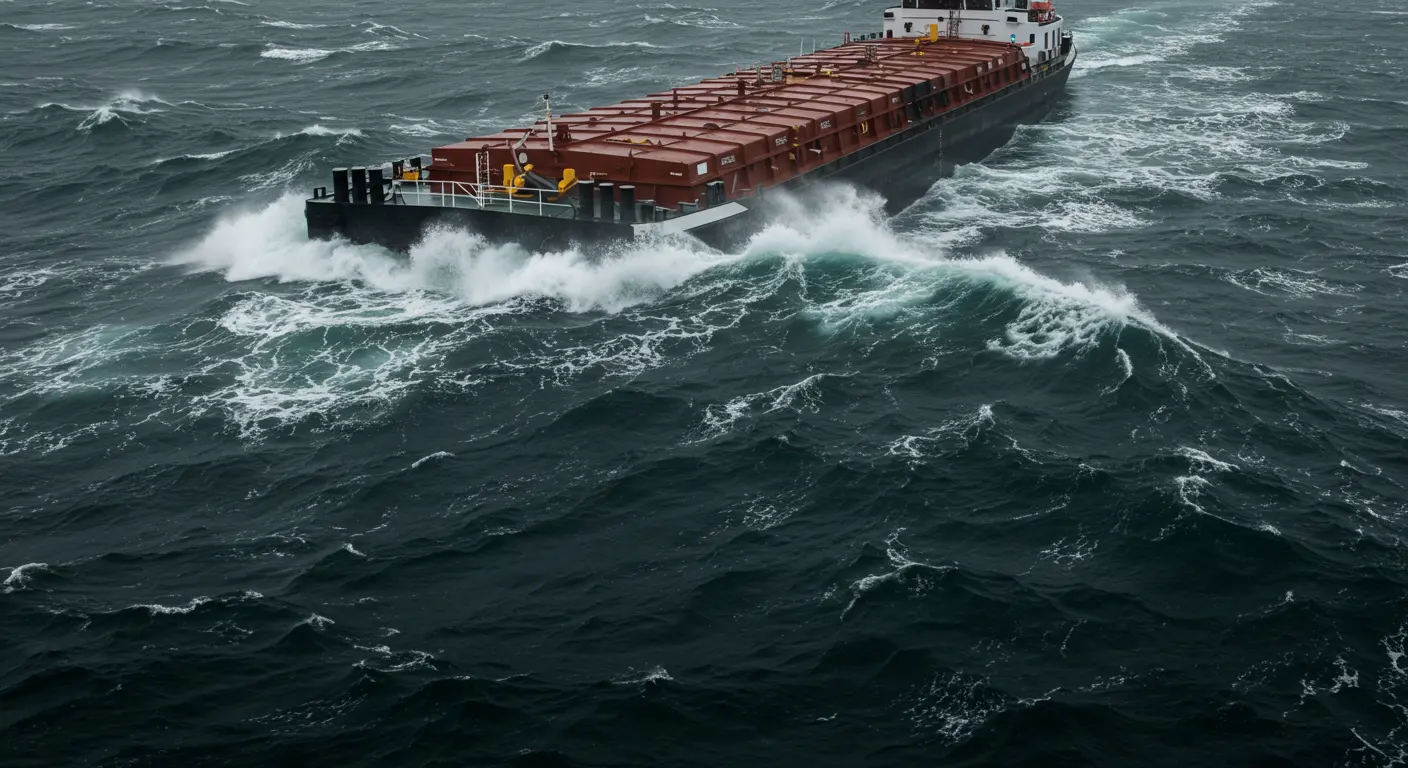
When a vessel sinks in bad weather, the obvious explanation is the weather. But the cause of a marine loss is rarely that simple. Adjusters have to decide whether the loss was an Act of God, a natural event that could not reasonably have been foreseen or guarded against, or whether negligence in maintenance, operation or loading played a part.
This article looks at an anonymised claim for the total loss of a leased barge in Nigerian waters, insured under a Marine Hull and Machinery policy. It covers how cause was established without access to the wreck, how the lease agreement shaped liability, and how a failed recovery against the lessee reduced the settlement.
Act of God, negligence and contracts
Marine insurance responds to fortuitous losses from perils of the sea such as sinking, collision, grounding, fire and heavy weather. It does not respond to inherent vice or ordinary wear and tear.
An Act of God is generally a direct, violent and irresistible act of nature, such as an exceptionally severe storm. Negligence is a failure to take the care expected in the circumstances: poor maintenance leading to unseaworthiness, errors in seamanship or in handling the vessel, or improper loading. The distinction matters because seaworthiness and maintenance warranties often turn on whether the insured exercised due diligence.
Charter parties and lease agreements add a further layer. They often allocate responsibility for loss or damage between owner and charterer or lessee. That affects where liability sits and whether the insurer can recover its outlay from a third party through subrogation.
The barge and the lease
The vessel, which we will call Barge Alpha, was a ramp barge owned by a leasing company and insured under a standard Hull and Machinery policy. It was leased to a cargo owner to carry containerised cargo within Nigerian waters.
- Vessel condition: the barge was not new, but it had been dry-docked, sandblasted and re-plated about a month before the loss. The owner held a valid Nigerian Load Line Certificate and a Boat Licence issued by the Nigerian Maritime Administration and Safety Agency (NIMASA).
- Operational control: under the lease, the cargo owner had full control. It loaded the cargo and hired the tug and crew separately. No one from the insured leasing company was on the barge or the tug during the voyage.
- Liability under the lease: the agreement made the cargo owner responsible for any loss or damage to the barge while in its control.
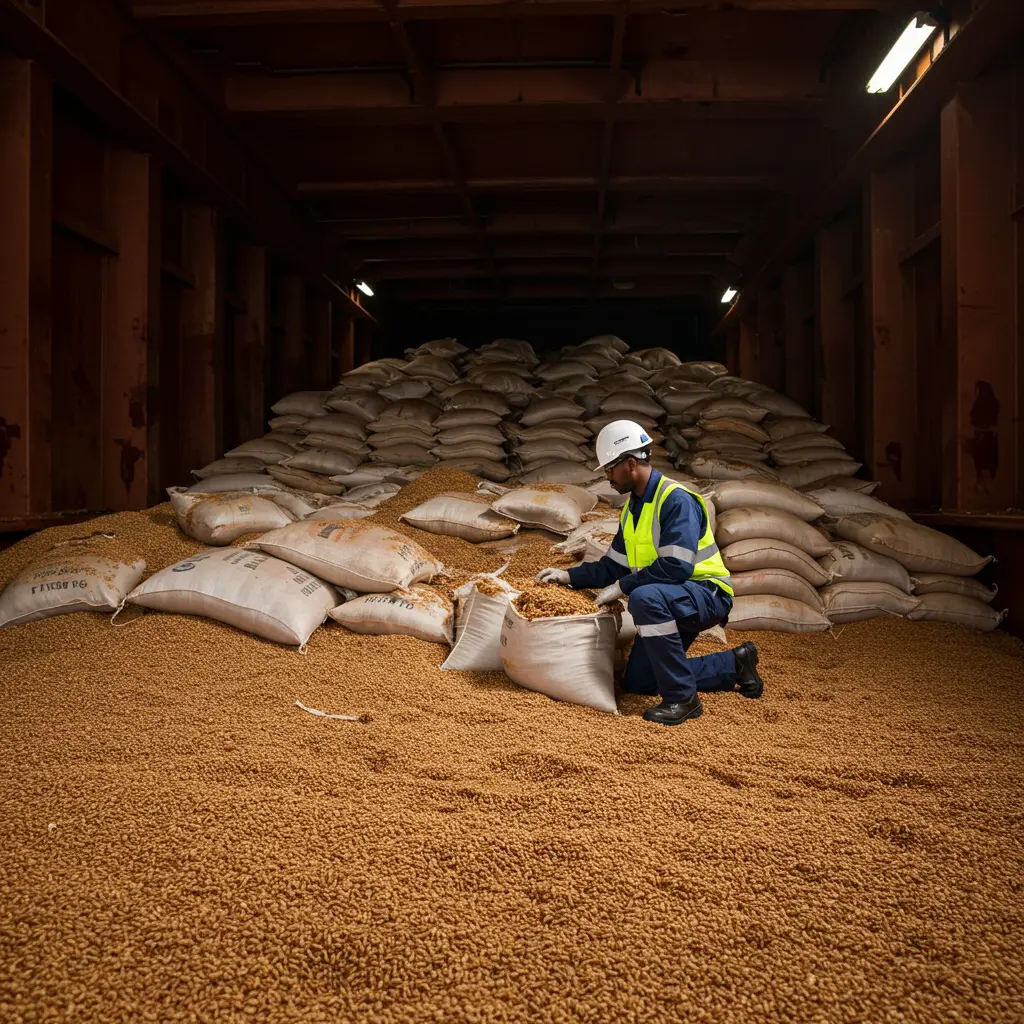
- Cargo: the barge carried thirty-two 20ft containers of scrap, including heavy items such as engines and machinery. There was no log of the total container weight.
The sinking and our investigation
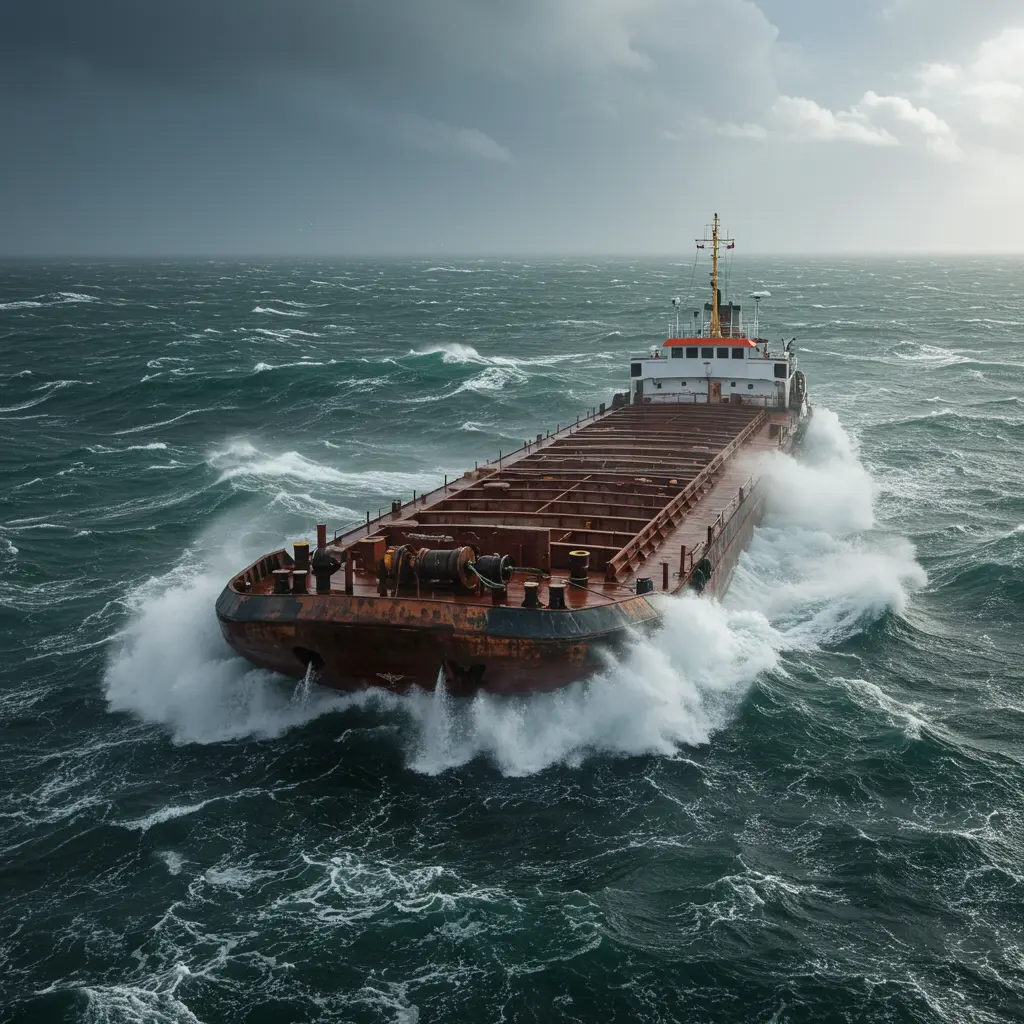
On the return voyage, under tow, the barge met heavy rain and high seas. The tug crew saw significant water coming into the barge and deployed pumps, but the high tide and rough sea overwhelmed them. The barge listed under the weight of the water and the containers, then sank with all its cargo. The tug crew disconnected safely.
The barge could not be recovered from the seabed, so physical inspection was impossible. Insurers appointed us, and we:
- interviewed key personnel at the leasing company and the cargo owner;
- reviewed the tug crew's incident report and the Police Sea Disaster Investigation Report;
- examined the barge's certificates and the lease agreement.
A consulting marine engineer considered whether the weight of the scrap cargo had made the barge unstable, which would point to overloading. Without a weight log, this could not be confirmed. The police report attributed the sinking to "barge leakages" but also stated that the tug and barge were seaworthy and the crew competent before the voyage.
As the barge was unrecoverable, the claim was treated as a total loss. The claim was based on replacement cost, supported by a voucher for the original construction cost, which we accepted as reasonable under the policy conditions.
How the policy responded
Cause. The recent dry-docking and valid certificates supported pre-voyage seaworthiness. On the evidence available, we concluded that the proximate cause was perils of the sea in heavy weather, an Act of God. We reached that view while recognising the suspected overloading and the leakages noted by the police, neither of which could be proven as the cause.
Warranties. The documents confirmed compliance with the seaworthiness and maintenance warranties.
Recovery. The lease placed liability for the loss on the cargo owner, and the leasing company pursued it for the replacement cost, as the policy required. The cargo owner said it could not pay, citing its own losses from the cargo that went down. That left the insurer's subrogation rights prejudiced, and we applied a 50% deduction from the otherwise agreed settlement.
Excess. The 15% total loss excess was then deducted from the remaining amount.
What the case shows
Heavy weather was the proximate cause, but it did not decide the outcome on its own. The loading practices and the lessee's failure to honour the lease shaped the final figure as much as the storm did.
Certificates and dry-docking records carried real weight in our finding, but they show the certified condition of a vessel, not necessarily its fitness for a particular voyage with a particular cargo. The missing weight log meant overloading could be neither confirmed nor ruled out.
With no wreck to examine, the finding rested on documents and witness accounts: the tug crew's report, the police report, the certificates and the lease. Gathering all of them mattered. Where the evidence is incomplete, the adjuster has to weigh what is confirmed, such as valid certificates and a recent dry-docking, against what is suspected but unproven, such as overloading, and say clearly which way the balance falls.
For a vessel on lease, the lessee's standards and cargo handling become part of the risk, even when the owner maintains the vessel well.
Lessons for insurers and claims managers
- Rule out negligence before finding Act of God. Even where severe weather is clear, look at maintenance, operational decisions and loading before settling on a natural cause.
- Look behind the paperwork. Certificates matter, but ask what the vessel was actually carrying and how it was being operated.
- Ask for operational records early. Cargo weights and loading logs can decide causation when the wreck cannot be inspected.
- Read the lease or charter party at the start. Its liability clauses identify the responsible party and the route to recovery.
- Brief insureds on protecting recovery rights. If a contractually liable party does not pay, for whatever reason, the claim can be cut substantially.
- Underwrite leased vessels with the lessee in mind. The lessee's experience, operating standards and cargo carry the risk, and the policy should address third-party operation.
- Share claim findings with underwriters. Gaps between certified and actual condition, lessee practices and weak contract terms should inform future risk assessment.